Health Spending Accounts and Wellness Spending Accounts

Health Spending Accounts and Wellness Spending Accounts

Running a business in Canada involves balancing expenses, employee satisfaction, and adapting to the evolving benefits landscape. As healthcare costs rise and workplace wellness becomes increasingly important, many business owners seek effective ways to support their employees without incurring unsustainable costs.

Health Spending Accounts (HSA) and Wellness Spending Accounts (WSA) offer flexible, customizable benefits that can help you:

  • Provide meaningful support to your team

  • Reduce taxable income

  • Offer personalized coverage that meets diverse employee needs

If you’re considering enhancing your benefits strategy, here’s what you need to know.

Understanding the Difference: HSA or WSA

Health Spending Accounts

A Health Spending Account is an employer-funded plan that reimburses employees for a wide range of CRA-approved medical expenses—from dental work and prescription glasses to therapy and treatments from licensed practitioners. These accounts are CRA-compliant, meaning all expenses must meet government eligibility guidelines to maintain their tax advantages.

Unlike wellness accounts, HSA reimbursements are non-taxable for employees and fully tax-deductible for employers, making them a smart, cost-effective way to offer health benefits.

Eligible categories typically include:

  • Vision – Exams, glasses, contacts, laser surgery

  • Dental – Cleanings, fillings, orthodontics

  • Prescription Drugs – Any medications prescribed by a licensed practitioner

  • Mental Health – Therapy, counselling by qualified professionals

  • Medical Equipment & Services – Devices and treatments provided by licensed health practitioners

Wellness Spending Accounts

A Wellness Spending Account is an employer-funded plan that provides employees with a taxable allowance to support their overall well-being—covering a wide range of lifestyle and preventative health expenses beyond traditional medical care. These accounts are not governed by CRA medical expense rules, which means employers have the flexibility to define which expenses are eligible.

Unlike Health Spending Accounts, WSA reimbursements are taxable for employees but remain fully tax-deductible for employers, making them a versatile and customizable way to promote wellness in the workplace.

Common categories covered by a WSA include:

  • Nutrition – Supplements, meal plans, counselling

  • Fitness – Gym memberships, equipment, classes

  • Mental Health – Therapy, mindfulness tools, retreats

  • Professional & Personal Development – Courses, seminars, learning tools

  • Personal & Family Interests – Music, art, parenting programs

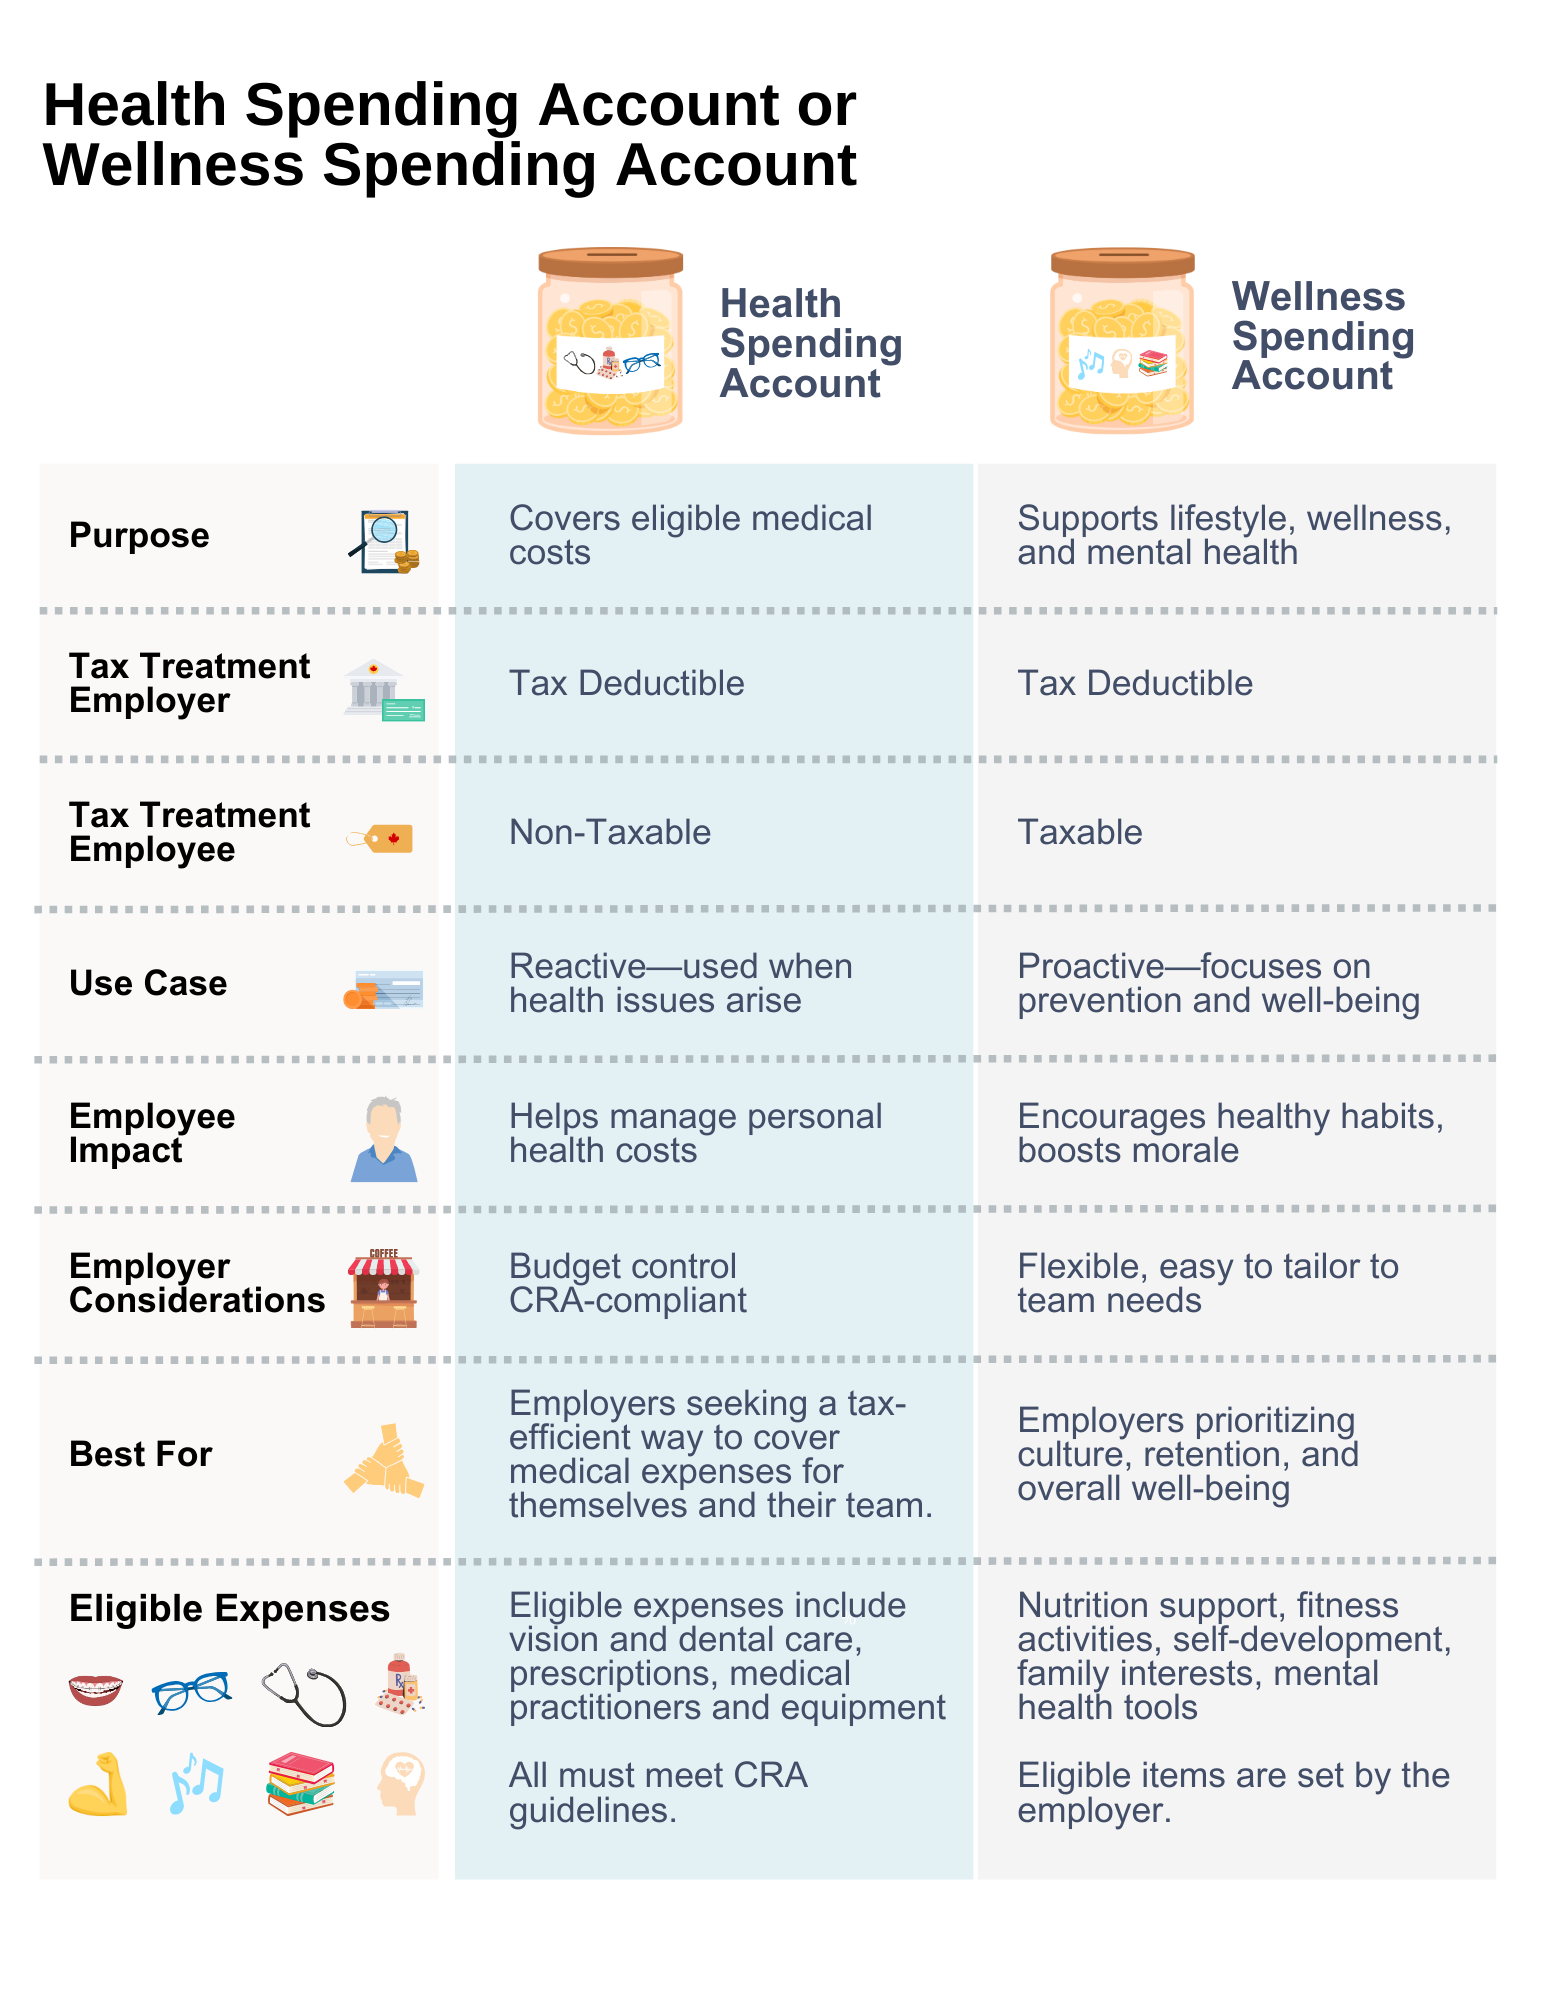
Health Spending Account vs. Wellness Spending Account

When it comes to supporting your team’s health and well-being, flexibility matters. This quick comparison breaks down how each account works, what’s covered, and how they can support both your employees and your bottom line.
brandableContent

Why More Business Owners Are Using Spending Accounts

HSA and WSA work alongside traditional plans: Many employers use HSAs/WSAs to complement existing coverage, offering added flexibility where employees need it most.

HSAs and WSAs offer:

  • Cost Predictability: Set annual maximums to control benefits spending.

  • Flexibility: Customize eligible expenses to align with employee needs and company culture.

  • Employee Satisfaction: Provide personalized benefits that can enhance morale and retention.

How It Works

  • Choosing a Provider: Many insurance providers offer these accounts as add-ons.

  • Allocating Funds: Decide how much to allocate per employee annually (e.g., $1,500 for HSA and $500 for WSA).

  • Reimbursement Process: Employees submit receipts for eligible expenses and receive reimbursements, subject to plan guidelines.

Getting Started

  • Assess Needs: Evaluate your team’s needs and preferences.

  • Select a Provider: Choose a provider that offers the level of customization and support you require.

  • Communicate: Clearly explain the benefits and usage of the accounts to your employees.

  • Monitor and Adjust: Regularly review the program’s effectiveness and make adjustments as needed.

Health and Wellness Spending Accounts provide Canadian business owners with flexible, tax-efficient tools to support their employees’ health and well-being. By offering these benefits, you can enhance employee satisfaction, control costs, and create a supportive workplace culture. Need help applying this to your situation? Book a quick call with our team.

Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or tax advice. Always consult a qualified professional regarding your specific situation. We are not responsible for any actions taken based on this content.

Sources:

5 Emerging Trends in Group Benefits Every Employer Should Know

Employee expectations are shifting, and group benefits are no longer one-size-fits-all. Employers across Canada are recognizing that competitive compensation extends beyond salary. A strong benefits package can make the difference between attracting top talent and losing them to competitors. So, what’s new in group benefits, and why should employers pay attention?

How Group Benefits Are Evolving

Traditionally, group benefits focused on basics like health, dental, and life insurance. While these remain important, employees are now looking for flexibility, mental health support, and programs that reflect their diverse needs. The COVID-19 pandemic accelerated many of these changes by highlighting the importance of health, security, and work-life balance. As the workplace continues to evolve, organizations must ensure their benefits keep pace with these expectations.

Employers that adapt can improve retention, boost morale, and reduce turnover costs. Ignoring these shifts could leave organizations struggling to keep up in a competitive hiring market. With skilled workers in high demand, especially in certain industries, a forward-looking approach to group benefits is becoming just as important as compensation.

Why It Matters for Employers

Employees increasingly view benefits as a reflection of company culture and values. Offering modern benefits demonstrates care for employee well-being while also positioning the company as progressive and people-focused. In today’s workplace, benefits are no longer a “perk” but an expectation.

Research shows that employees who feel supported in their overall wellness are far more likely to remain with their employer over the long term. This means a strong group benefits package is not only about attracting new hires but also about retaining existing talent. Employers who stay ahead of these trends can stand out as attractive places to work, while those who fall behind may face higher turnover, lower engagement, and increased costs associated with rehiring and training.

Five Key Trends in Group Benefits

1. Personalized and Flexible Benefits

One of the biggest shifts is the move toward customizable plans. Instead of a standard package that offers the same benefits to all employees, many employers now offer flexible health spending accounts or wellness allowances. This allows employees to choose what’s most relevant to their lifestyle, whether it’s vision care, gym memberships, or alternative therapies such as acupuncture or massage.

For example, a young professional may prioritize fitness and mental health services, while a parent with young children may value vision and dental coverage. Providing flexibility ensures employees feel supported no matter their stage of life. Employers who give choice not only meet diverse needs but also show respect for their workforce’s individuality.

2. Mental Health and Well-Being Support

Mental health has become a central focus of workplace benefits. Over the past few years, stress, anxiety, and burnout have risen significantly, with many employees seeking more support from their employers. Companies that provide access to counseling, therapy, and stress management programs are seeing stronger employee engagement and resilience.

Some employers are expanding Employee Assistance Programs (EAPs) to include ongoing counseling sessions rather than short-term solutions. Others are investing in digital platforms that connect employees to licensed therapists through apps or online services. Mindfulness subscriptions, mental health days, and manager training on how to support struggling employees are also gaining popularity.

Investing in mental health doesn’t just benefit employees—it also reduces absenteeism and improves productivity. According to the Mental Health Commission of Canada, mental health problems cost the economy billions annually in lost productivity. By prioritizing well-being, employers help create a healthier and more sustainable workplace.

3. Virtual and Digital Health Care

Virtual care has moved from being a “nice-to-have” to a standard expectation. Employees value quick and easy access to healthcare professionals through telemedicine and online consultations. This is especially beneficial for remote or rural employees who may not have easy access to clinics.

Virtual healthcare services can include online doctor visits, prescription renewals, chronic disease management, and even physiotherapy consultations. These services not only improve convenience but also reduce the number of sick days taken for medical appointments. Employers offering virtual healthcare are finding that employees appreciate the time savings and accessibility.

The rise of digital health has also led to innovations such as wearable devices and health apps that help employees track their physical activity, sleep, and nutrition. Employers who integrate these tools into wellness programs can foster healthier habits across their workforce.

4. Financial Wellness Programs

More employers are including financial literacy tools, budgeting workshops, and retirement savings programs as part of their group benefits. With rising living costs and household debt levels, employees are increasingly worried about financial security. These concerns directly impact workplace focus and productivity.

Financial wellness programs may include one-on-one financial coaching, webinars on debt reduction strategies, or tools to help with budgeting and savings. Some employers even offer employer-matching programs for retirement savings or assistance with student loan repayments. Supporting financial well-being helps reduce stress, increases employee satisfaction, and builds long-term loyalty.

In many ways, offering financial support demonstrates the employer’s recognition of real-world challenges employees face. When workers feel supported in managing their finances, they are less distracted, more motivated, and better able to contribute fully at work.

5. Non-Traditional Benefits

Beyond the usual health and dental, employees are showing interest in perks that support their lifestyle and overall happiness. Non-traditional benefits can range widely but often focus on work-life balance and unique employee needs.

Examples include:

  • Pet insurance for employees who consider pets part of the family.

  • Childcare support such as daycare subsidies or backup care services.

  • Professional development allowances that fund courses, certifications, or conferences.

  • Wellness stipends for home office upgrades, fitness equipment, or meal delivery services.

  • Extra vacation days or volunteer time-off programs that support work-life integration.

  • Fertility and in vitro treatment coverage, which has become a highly valued benefit for employees who want support in building their families.

These offerings not only stand out to potential hires but also foster loyalty among existing staff. They signal that the employer is forward-thinking and understands the broader needs of today’s workforce. In competitive industries, non-traditional benefits can be the deciding factor for a candidate weighing multiple job offers.

Bringing It All Together

Group benefits are no longer just about coverage—they are about connection. Employers who embrace these trends send a clear message: we care about your well-being, both at work and beyond. By investing in flexible, supportive, and forward-looking benefits, companies can strengthen employee loyalty and position themselves for long-term success.

As you review your group benefits program, consider which of these trends could align with your workforce’s needs. Even small adjustments—like adding flexible spending options or introducing virtual care—can have a big impact on employee satisfaction. When employees feel supported, they are more engaged, more productive, and more likely to stay for the long term.

This is for informational purposes only and does not constitute financial, legal, or tax advice. Always consult a qualified professional regarding your specific situation. We are not responsible for any actions taken based on this content.

Renewing Your Group Benefits Plan

When it’s time to renew your organization’s group benefits plan, it’s a chance to step back, take a close look, and ensure everything still makes sense for your team and budget. Each year, your provider will review past claims and usage to help adjust coverage and premiums, so the plan remains relevant. Here’s how to get the most out of this process.

Reviewing Your Benefits: Focus on What Matters

Take time to examine each part of your benefits package to see if it still meets the needs of your team:

  • Health Coverage: Look at what’s covered for prescription drugs, hospital care, and specialist visits. Are the current limits in line with what your team uses most?
  • Dental Coverage: From cleanings to crowns, check that the plan covers routine and advanced dental needs. If usage is low, maybe it’s time for an update.
  • Disability and Life Insurance: Disability insurance protects income during tough times, while life insurance gives peace of mind. Make sure coverage levels are right for your team.
  • Critical Illness and Accident Insurance: These benefits can provide extra financial support for serious illnesses or accidents, with options for additional coverage if it’s a priority for employees.

Specialty Benefits That Add Flexibility

Consider adding options that give employees more control over their benefits:

  • Health Care Spending Accounts (HCSAs): With HCSAs, employees have a set allowance to cover eligible health expenses. This flexibility lets employees pick and choose the coverage that fits their needs.
  • Emergency Medical Coverage: This can be particularly valuable for employees who travel frequently, covering unexpected medical costs on the road.
  • Retiree and Self-Employed Benefits: If you offer benefits for retirees or contractors, make sure these plans focus on the essentials, like prescriptions, dental, and vision, to keep things simple and effective.

Checking Value and Staying on Budget

Once you know what you’re covering, see if it aligns with what your team values most and if it’s worth the premium cost:

  • Utilization Analysis: Look at which benefits are most used. If something like dental care isn’t being used much, that could mean there’s room to adjust.
  • Employee Feedback: Ask employees directly what benefits do they find most valuable? This feedback can guide your decisions.

Making the Right Adjustments

When you have the full picture, it’s time to consider if adjustments would make the plan stronger or more efficient:

  • Benefit Modifications: Maybe it’s time to add a health spending account, adjust critical illness coverage, or tweak other benefits to better reflect what employees want.
  • Cost-Sharing Adjustments: Evaluate how the premium costs are split. Adjusting the cost share may help keep the plan sustainable for everyone.

With the right approach to your group benefits renewal, you can keep your plan valuable, easy to understand, and tailored to what your team needs most. This way, you’re not just offering a benefits package—you’re providing a solution that works.

Protecting Key Talent using Group Benefits

Building a Sustainable Future Together

As specialists in group benefits, the primary goal is to cultivate a sustainable future by collaborating closely with clients. The belief is that an informed and engaged workforce is pivotal for the success of any organization. A key component of this vision is the protection of the organization’s essential talent. This article delves into how group benefits can be instrumental in safeguarding an organization’s most treasured resource: its people.

The Importance of Essential Talent

Essential talent encompasses those employees who bring critical skills, expertise, and knowledge that propel an organization’s growth and success. These individuals form the core of any organization, ensuring its prosperity in the competitive market. Retaining such invaluable members is crucial as their absence can significantly affect business operations, productivity, and overall morale.

Challenges in Retaining Essential Talent

In the ever-evolving job market, holding onto essential talent can be a daunting task. Numerous factors, including enticing offers from rivals, opportunities for personal growth, work-life equilibrium, and employee well-being, can influence retention. For employers, recognizing and addressing these challenges is vital to safeguard top performers and sustain a competitive advantage.

The Significance of Group Benefits

Group benefits serve as a potent strategy in attracting and retaining essential talent. By presenting comprehensive and tailored benefits packages, organizations showcase their dedication to the well-being, security, and future of their employees. Here are some pivotal aspects of group benefits that aid in retaining essential talent:

  1. Health and Wellness Coverage: Offering comprehensive health and wellness benefits, such as medical, dental, and vision plans, not only fosters a healthy workforce but also signifies an organization’s commitment to overall employee well-being. Employees who feel this support are more inclined to stay loyal.
  2. Income Protection: Many group benefits packages encompass disability insurance, offering financial security for employees facing injuries or illnesses that hinder their work. Such provisions alleviate financial concerns during tough times, fostering a sense of stability and encouraging talent to remain with the organization.
  3. Retirement Planning: A meticulously crafted retirement plan appeals to essential talent. It signifies an organization’s concern for their future and dedication to ensuring their financial comfort during retirement. Contributing to such plans also strengthens the bond between employers and employees.
  4. Support for Work-Life Balance: Benefits that champion work-life balance, like flexible work schedules, paid leaves, and family leaves, reflect an organization’s understanding of the significance of a balanced life. Employees who sense this flexibility are more likely to remain devoted.
  5. Career Advancement: Benefits can also encompass professional development and training opportunities. Investing in employee growth not only sharpens their skills but also underlines an organization’s commitment to their long-term achievements.

Educational Approach and Teamwork

The role of group benefits specialists is to offer educational support and foster collaboration with clients. Through open dialogues about an organization’s aspirations and needs, it’s possible to design group benefits packages that resonate with specific demands. The collective goal is to nurture and protect essential talent, ensuring a sustainable future.

Protecting essential talent through group benefits is more than a strategic move; it embodies a dedication to employee welfare. By investing in the well-being, security, and future of employees, organizations not only boost loyalty and retention but also lay the foundation for a robust and sustainable future. The journey ahead is one of partnership, aiming for a flourishing and vibrant workforce.

Exploring the Value of Group Benefit Plans for Your Employees

In today’s ever-evolving workplace landscape, employees place a premium on several key factors:

1. Alignment with employer values, especially sustainability.

2. Achieving a harmonious work-life balance.

3. Assistance in coping with the rising cost of living expenses.

4. Opportunities for delayed retirement.

5. Cultivating a sense of belonging within the workplace.

6. Flexibility in terms of work hours and location.

7. Ensuring job security.

If your business is experiencing growth and you’re considering adding group benefit plans to your employee offerings, you’re in the right place. We understand the importance of providing the right employee benefits solution for your business.

Understanding Group Benefit Plans and Their Value

Group benefit plans form a crucial part of a company’s total compensation package, available to employees regardless of their seniority, position, or qualifications. These plans often encompass medical coverage for employees and their dependents. While it may seem like an additional expense during a period of growth, offering employee insurance benefits is essential for the long-term sustainability of your business.

So, why should your company consider offering group insurance benefits? Here are some compelling reasons:

1. Convenience: Group insurance benefits simplify healthcare coverage for your employees and their families.

2. Workforce Protection: These benefits provide a safety net for your staff, promoting their well-being.

3. Staff Retention: Offering benefits can help you retain valuable employees, reducing turnover.

4. Tax Benefits: Group insurance plans offer tax advantages for both employers and employees.

5. Customization: Plans can be tailored to meet your business’s unique needs.

6. Morale Boost: Providing benefits can boost productivity and morale among your workforce.

What’s Covered by Group Insurance Plans?

Group insurance plans typically cover medical-related expenses that provincial healthcare plans might not fully address. This coverage can include paramedical and ambulance services, dental care, eye care, hospital stays, and certain prescription drugs. Additionally, you have the option to combine group benefits plans with retirement and savings plans.

Types of Group Benefits Plans

Various types of group benefits plans are available, each catering to different company needs and preferences. The most popular options include:

1. Fully-Insured

2. Self-Funded

3. Level-Funded

No matter the size of your business, there’s a group insurance benefit plan that suits your needs. We offer flexible and innovative plans that anticipate your requirements. Our services aim to reduce your administrative workload, allowing you to focus on critical aspects of your business.

Is Group Insurance Cost-Effective?

One of the financial advantages of group insurance is lower premiums while maintaining coverage equivalent to individual health insurance. Typically, employers cover most of the group benefit plan costs, with employees contributing a small percentage of their salary towards the monthly premium. If you’re concerned about the tax implications of providing benefits at work, it’s advisable to with us for specific details.

In conclusion, offering group benefit plans is a strategic move to attract and retain top talent while promoting employee well-being and financial security. Whether you have a small or large business, we are here to assist you in finding the right plan that aligns with your organization’s needs and objectives.

Setting Up Your Employee Benefits Program

In the competitive landscape of today’s business world, an effective employee benefits program stands as a cornerstone of organizational success. Such programs not only serve as magnets for top talent but also highlight an organization’s unwavering commitment to the holistic well-being of its workforce.

Establishing a Benefits Budget
The foundation of a robust benefits program is a well-thought-out budget. By assessing the financial health of your organization, you can determine the funds you’re willing to allocate towards a comprehensive employee benefits package. It’s essential to delve deep into a cost analysis for each potential benefit, ensuring that the budget aligns with both the company’s capabilities and the employees’ needs.

Deciding on the Right Benefits
Once the budget is set, the next step is to curate the benefits that will form part of your program. Choices abound, from group health, dental, and vision insurance to paid time off, retirement savings plans, and flexible health savings accounts. There are also group life and disability insurance options, not to mention perks that foster a healthy work-life balance. While the budget will inevitably influence the selection, it’s paramount to weigh in the preferences and necessities of your employees.

Choosing a Benefits Provider
With a list of desired benefits in hand, the focus shifts to selecting the right provider. This involves researching providers that cater to your chosen benefits and juxtaposing the advantages and costs of each. Given the intricate nature of benefits plans, seeking expert advice can be invaluable in navigating this terrain and ensuring the best fit for your organization.

Finalizing the Benefits Program
After zeroing in on a provider, the next phase is to cement the details of your benefits program. This encompasses signing all requisite documentation and earmarking the date when the plan will kick off. While this might seem like a daunting task, remember that expert guidance can streamline the process, ensuring all i’s are dotted and t’s are crossed.

Communicating the Plan to Employees
The establishment of a benefits program is only half the battle. The other half is effective communication. Organize sessions to walk your employees through the nuances of the benefits plan, addressing any questions or concerns they might harbor. Furnish them with digital or printed copies of the benefits, elucidating both the costs they would incur and the contributions made by the company. It’s pivotal to ensure that every employee has a clear understanding of their benefits, coverages, and the provisions for their dependents. An online portal or resource can further empower employees to delve into their benefits at their own pace. And don’t forget to spotlight your benefits program on your organization’s career page and in job listings.

Tax Implications of Group Benefits
A noteworthy aspect of group benefits is their tax implications. Such benefits can be deducted before tax withholdings on an employee’s paycheck. For instance, if group health insurance premiums are covered by the organization, these amounts are eligible for deductions.

In Conclusion
Crafting a comprehensive employee benefits program is more than just a strategic move; it’s an investment in the future of the organization and its people. By adhering to the steps outlined, businesses can sculpt a benefits program that is both versatile and resonant, ensuring a harmonious and productive workplace.

Understanding Target Loss Ratio and Your Group Benefits Plan

Group benefits can be intricate both in their establishment and administration. There are numerous details and considerations to be aware of when purchasing a group benefits plan, one of which is the target loss ratio (TLR).

Key Questions Addressed:

  • What is a target loss ratio?

  • How does my TLR influence my premiums upon policy renewal?

  • What steps should I take if I have concerns regarding my TLR?

Understanding Target Loss Ratio (TLR):
Here are the primary aspects you should understand about the target loss ratio (TLR):

  • It represents the expected profit point of your employee benefit plan’s comprehensive health and dental benefits.

  • TLR is the maximum dollar amount of claims paid by the insurance company, expressed as a percentage of your premium. For instance, if an insurance company pays $40 in claims for every $80 collected in premiums, the loss ratio stands at 50%.

  • The TLR is primarily determined by two factors: the number of members participating in the employee benefit plan and the annual premium paid.

  • The loss ratios can vary based on the type of insurance. For instance, the loss ratio for property insurance is typically lower than that for health insurance.

Does my TLR Affect My Premiums Upon Renewal?
Generally, your TLR won’t have a significant influence on your premiums when renewing. However, a notable increase or decrease in the number of staff members participating in your group benefits plan might cause some impact.

Other factors influencing your renewal premiums include:

  • A substantial amount of health and dental claims made.

  • Changes in the general demographics of your employees, such as aging.

  • An increase in the cost of services covered by your group benefits plan.

  • General inflation.

Addressing Concerns About TLR:
As someone overseeing a group benefits plan, your objective is to ensure optimal value for your premium expenditure.

If you’ve been collaborating with the same insurance provider for an extended period, it’s beneficial to explore other available options. Comparing offerings can help ascertain if the rate and TLR you’re being offered align with current market standards.

It’s essential to consider how varying TLRs might influence the long-term viability of your group benefits plan. If you’re keen on gaining deeper insights, consider reaching out to industry experts or consultants for guidance.

Group Insurance vs Individual Life Insurance

Group Insurance vs Individual Life Insurance

“I already have life insurance from work, so why do I need to get it personally?” or “Work has got me covered, I don’t need it.”

While it’s great to have group coverage from your employer or association, in most cases, people don’t understand that there are important differences when it comes to group life insurance vs. self owned life insurance.

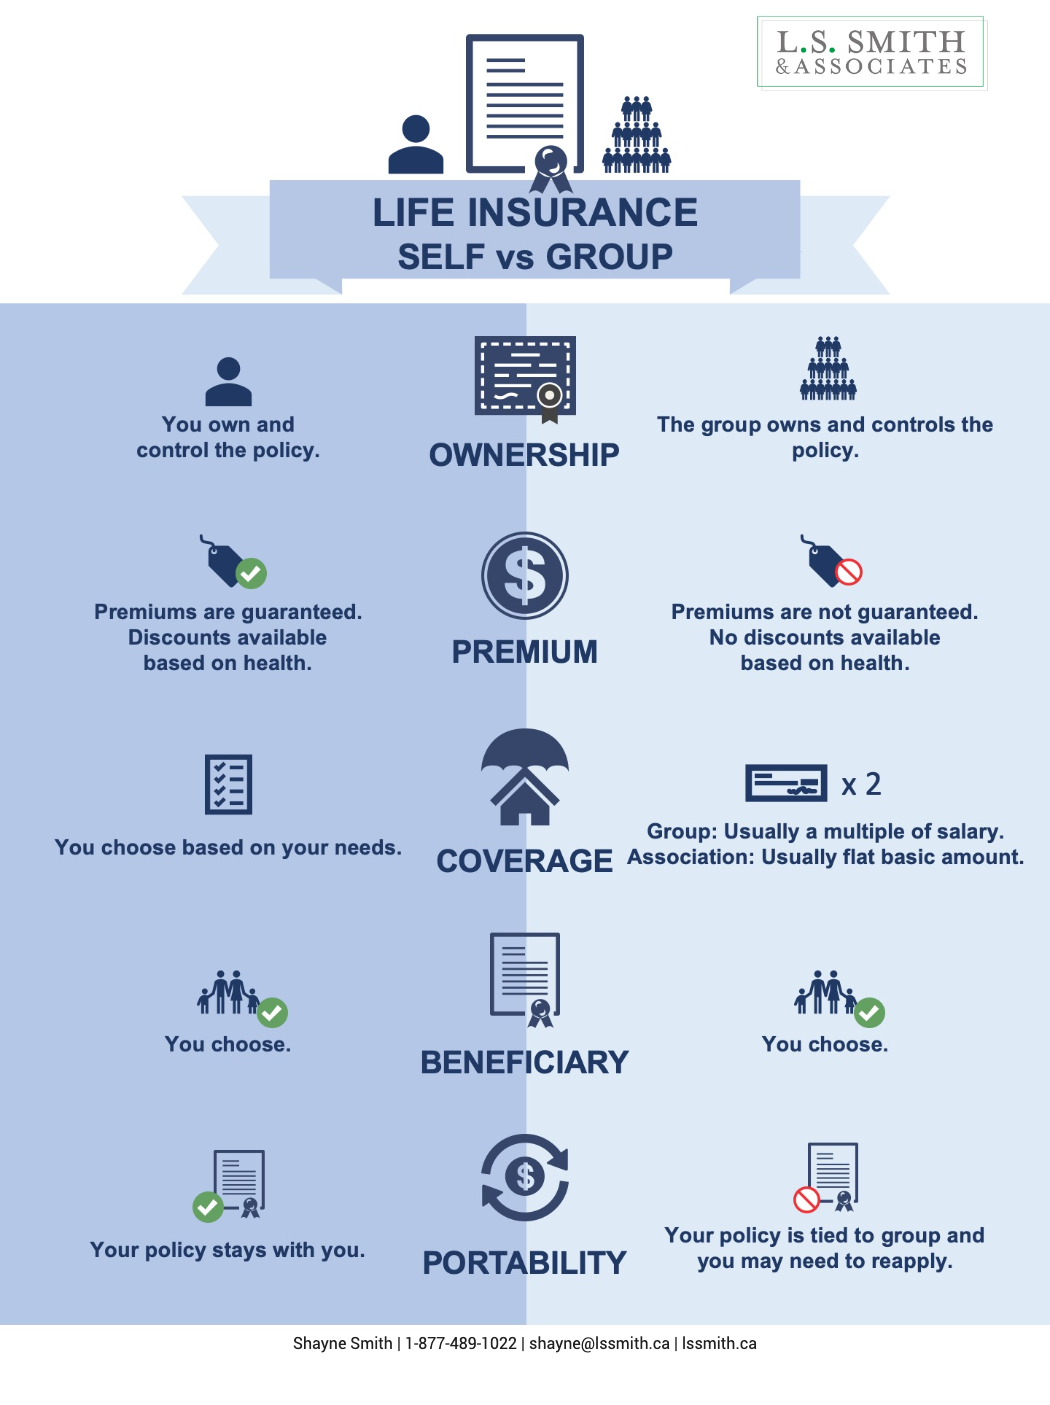
Before counting on insurance from your group benefits plan, please take the time to understand the difference between group owned life insurance and personally owned life insurance. The key differences are ownership, premium, coverage, beneficiary and portability.

Ownership:

  • Self: You own and control the policy.

  • Group: The group owns and controls the policy.

Premium:

  • Self: Your premiums are guaranteed at policy issue and discounts are available based on your health.

  • Group: Premiums are not guaranteed and there are no discounts available based on your health. The rates provided are blended depending on your group.

Coverage:

  • Self: You choose based on your needs.

  • Group: In a group plan, the coverage is typically a multiple of your salary. If your coverage is through an association, then it’s usually a flat basic amount.

Beneficiary:

  • Self: You choose who your beneficiary is and they can choose how they want to use the insurance benefit.

  • Group: You choose who your beneficiary is and they can choose how they want to use the insurance benefit.

Portability:

  • Self: Your policy stays with you.

  • Group: Your policy is tied to your group and if you leave your employer or your association, you may need to reapply for insurance.

Talk to us, we can help you figure out what’s best for your situation.

Defined Contribution vs. Benefit Pension Plan for Employees

The Key Differences Between a Defined Benefit and Defined Contribution Pension Plan

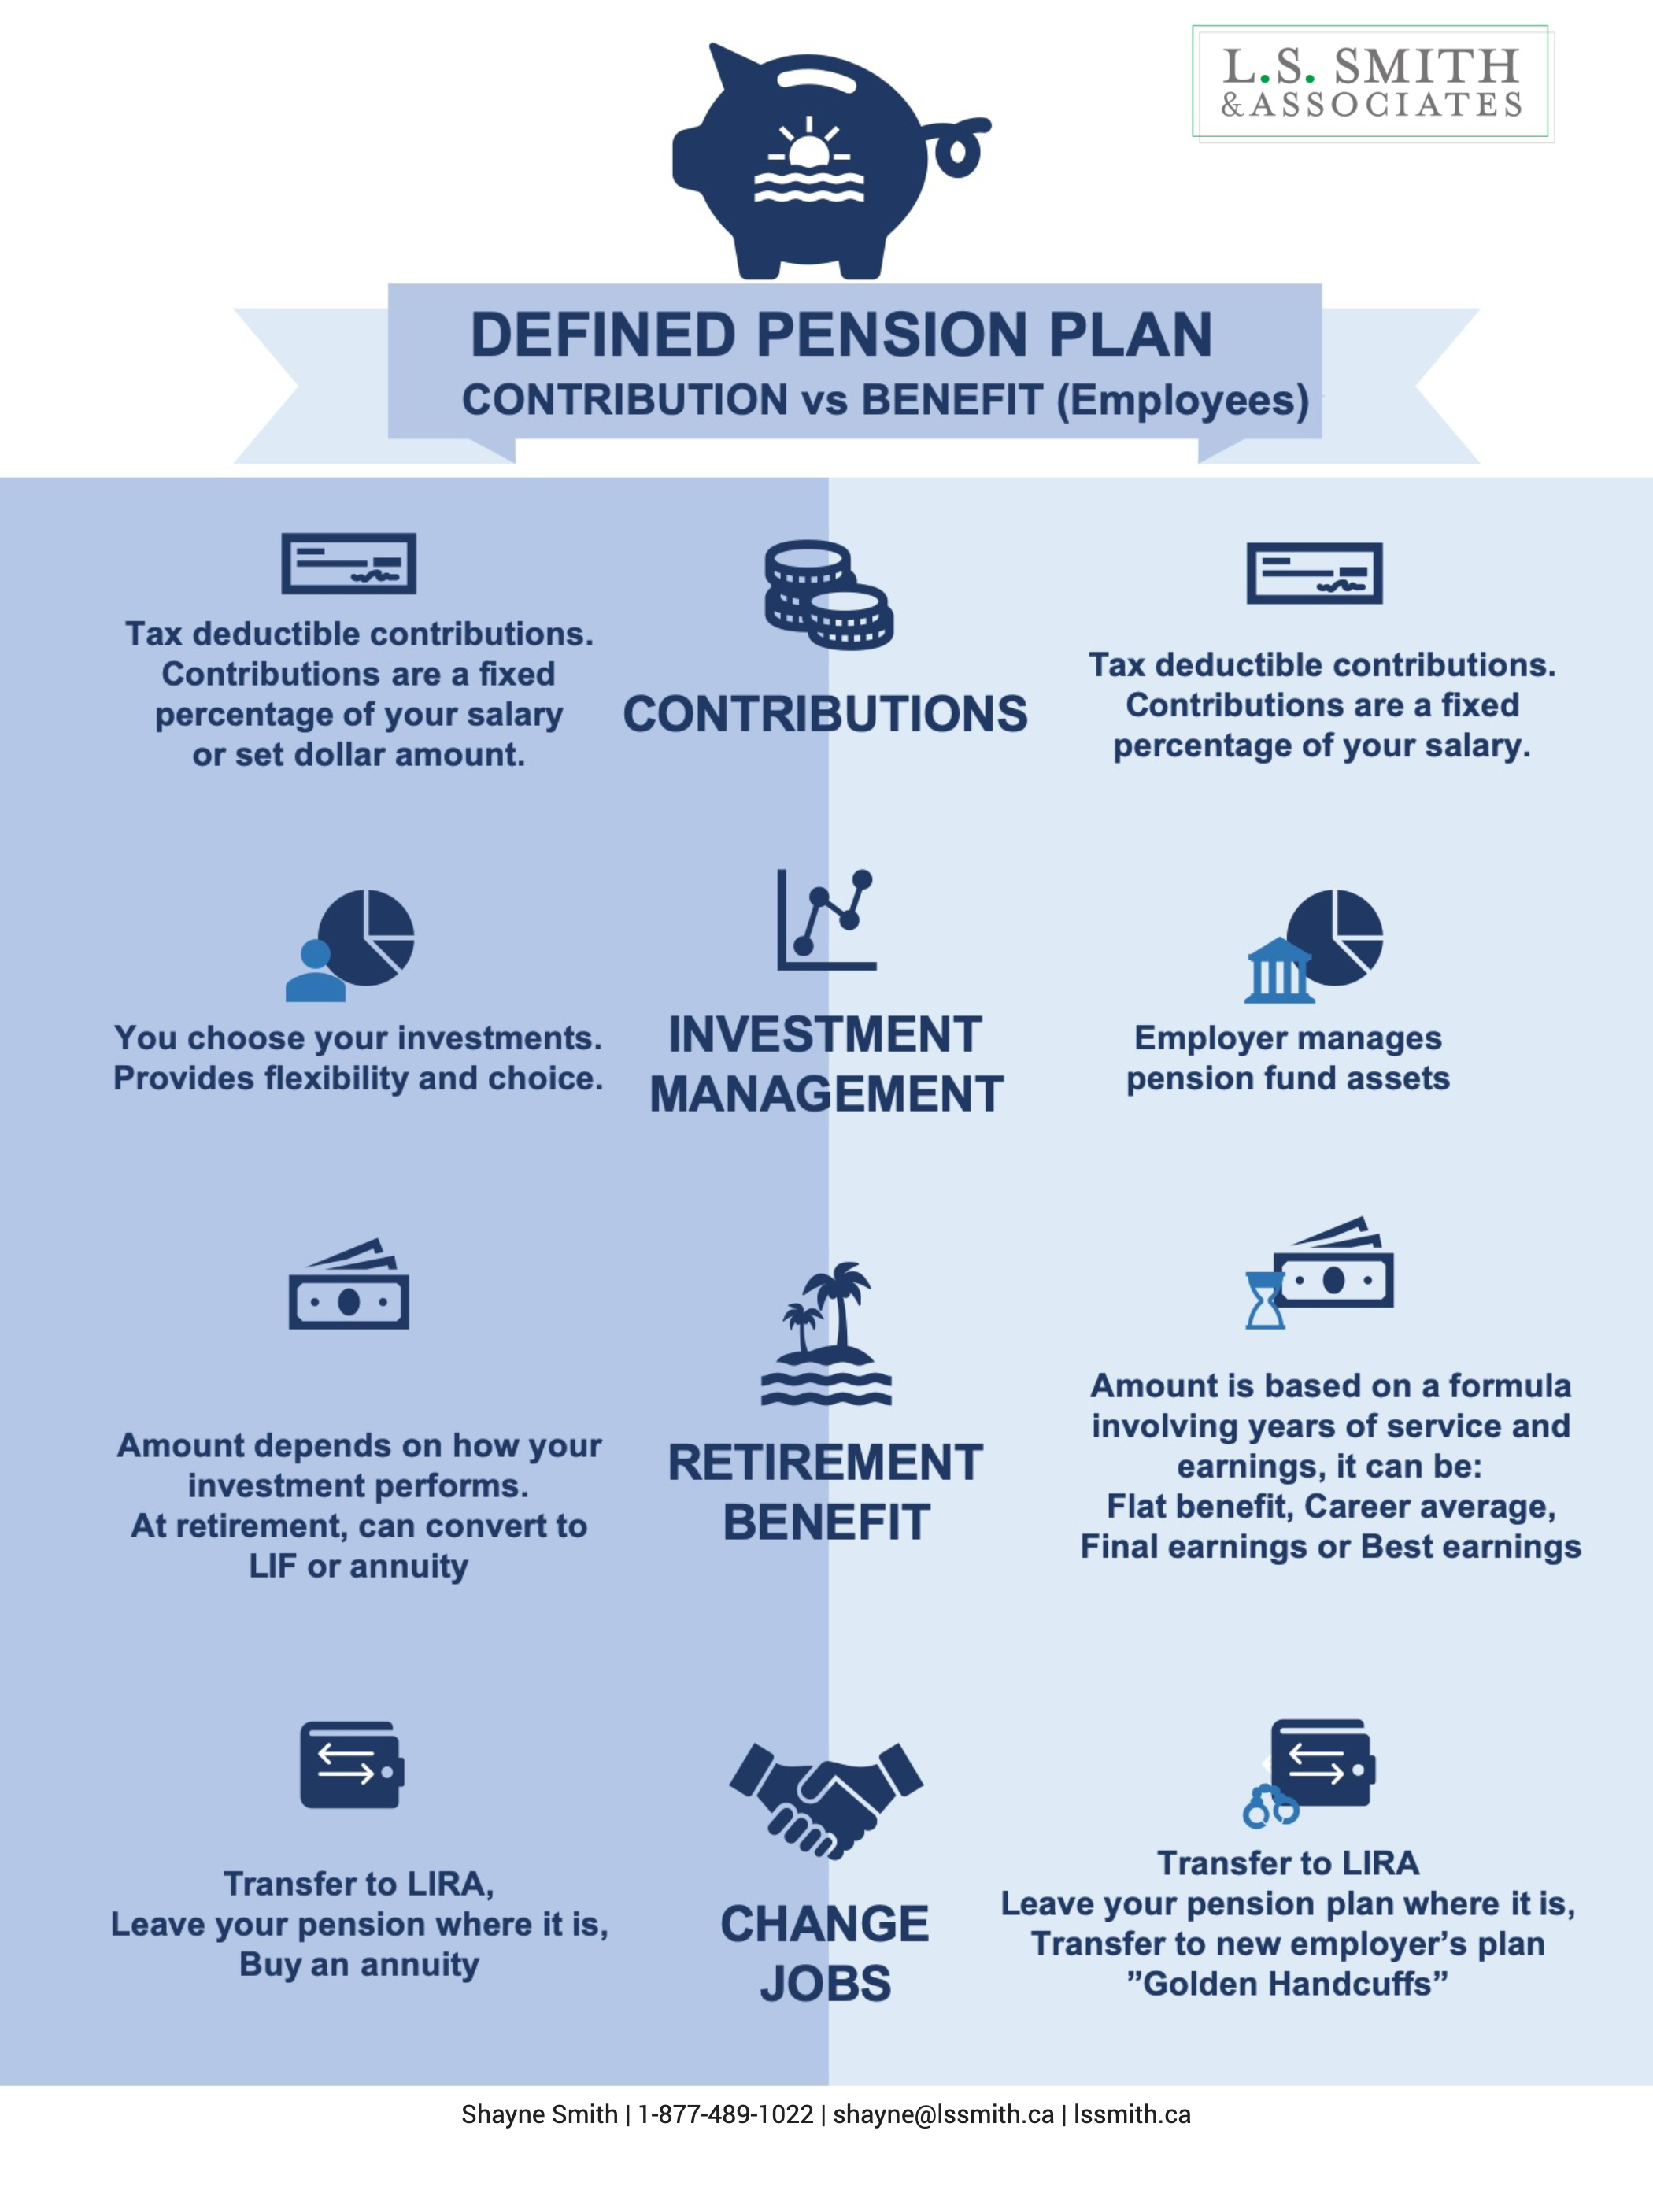
As an employer, you may be thinking about offering your employees a pension plan. If so, you have two main options: a defined benefit pension plan and a defined contribution pension plan. A defined benefit pension plan offers your employees a set amount of money when they retire, whereas a defined contribution pension plan does not.

There are four key areas you should be aware of for pension plans:

  • Contributions

  • Investment Management

  • Costs

  • Employee Retention

We will walk you through each of these to help give you a better understanding of the differences between the two types of pension plans.

Contributions

In a defined benefit pension plan, both you, the employer, and the employee will contribute to the pension plan. The amount that you will have to contribute each year will depend on what kind of expenses the pension plan has, and the amount of funding it will require that year.

In a defined contribution pension plan, employees contribute a set amount each year into their pension. As an employer, you can choose to match or “top up” their contributions to a set amount that you define in advance.

For both types of plans, contributions are tax-deductible for the employee.

Investment Management

As an employer, you or your pension plan administrator will be responsible for managing the funds in a defined benefit pension plan. This applies whether the employee is actively contributing to the fund or has retired and is receiving funds from it.

With a defined contribution pension plan, you can let your employees choose how they want to invest their funds. This provides your employees with more flexibility and choice and takes the responsibility off you as the employer to manage pension funds. You will still need to arrange to have a selection of funds for your employees to select from.

Costs

In a defined benefit pension plan, an actuary will work with you (approximately every three years) to calculate how much money you will need to cover the pension expenses. The actuary must consider everything from cost of living adjustments to how many employees will be retiring.

In a defined contribution plan, the costs will be lower as less active management is required. Employees will receive whatever amount their investments are worth when they retire.

Employee Retention

Both types of pension plans will help attract and retain employees. Since a defined benefit plan builds in value each year, it is more likely to attract employees interested in staying with your company for a long time. A defined contribution plan will still attract employees – but the pension will be less appealing than a defined benefit plan would be.

The Takeaway

A defined benefit plan will cost you more to set up, maintain, and administer, but offers your employees more stability in their retirement. A defined contribution plan will give you and your employees more flexibility and cost you less to run.

Either type of plan will help you attract and retain employees.

Group Retirement Benefits

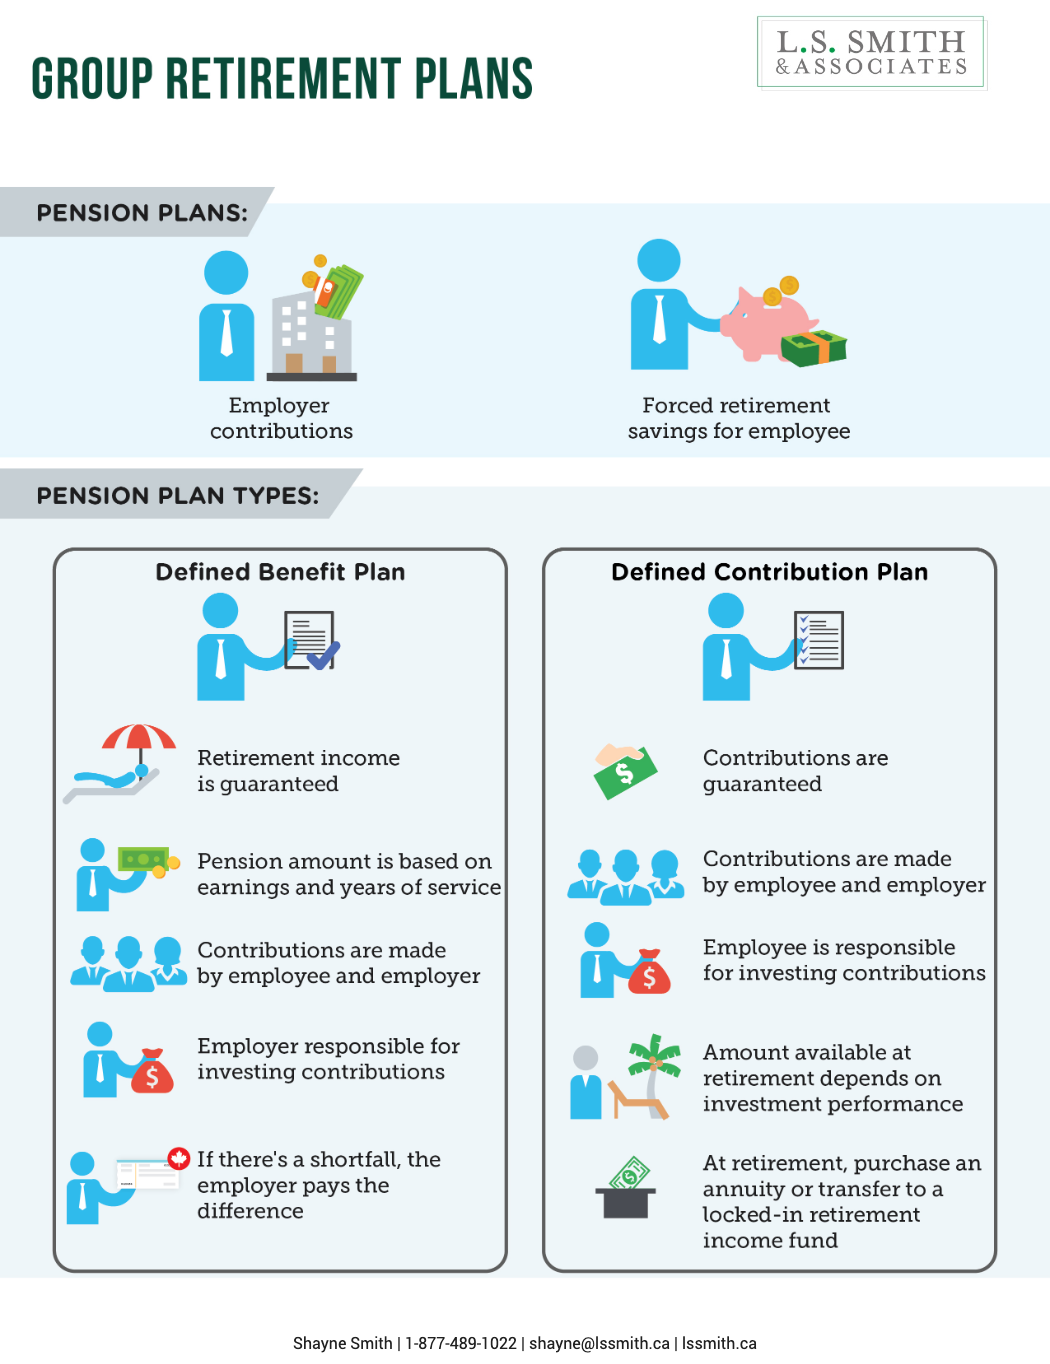
Working at an organization that offers a pension plan is one of the greatest financial advantages a Canadian can enjoy. Pension plans are designed to provide retirement income and help employees reach their retirement goals and for business owners- help retain key employees.

Pension plans can offer:

  • Employer contributions

  • Forced retirement savings for employee

There are 2 main types of pension plan:

  • Defined Benefit Plan

  • Defined Contribution Plan

Defined Benefit Plan

  • Retirement income is guaranteed, contributions are not.

  • The pension amount is based on a formula that includes the employee’s earnings and years of service with the employer

  • Usually, contributions are made by the employee and employer

  • The employer is responsible for investing the contributions to ensure there’s enough money to pay the future pensions for all plan members.

  • If there’s a shortfall, the employer pays the difference.

Defined Contribution Plan

  • Contributions are guaranteed, retirement income is not.

  • Usually, contributions are made by the employee and employer.

  • The employee is responsible for investing all contributions.

  • The amount available in retirement depends on how the investment performs including total contributions.

  • At retirement, the money in the account can be used to generate retirement income through purchasing an annuity or transferring the amount to a locked-in retirement income fund.

In summary, a defined benefits plan guarantees you a retirement income and a defined contribution plan guarantees contributions but not retirement income.

Talk to us, we can help.